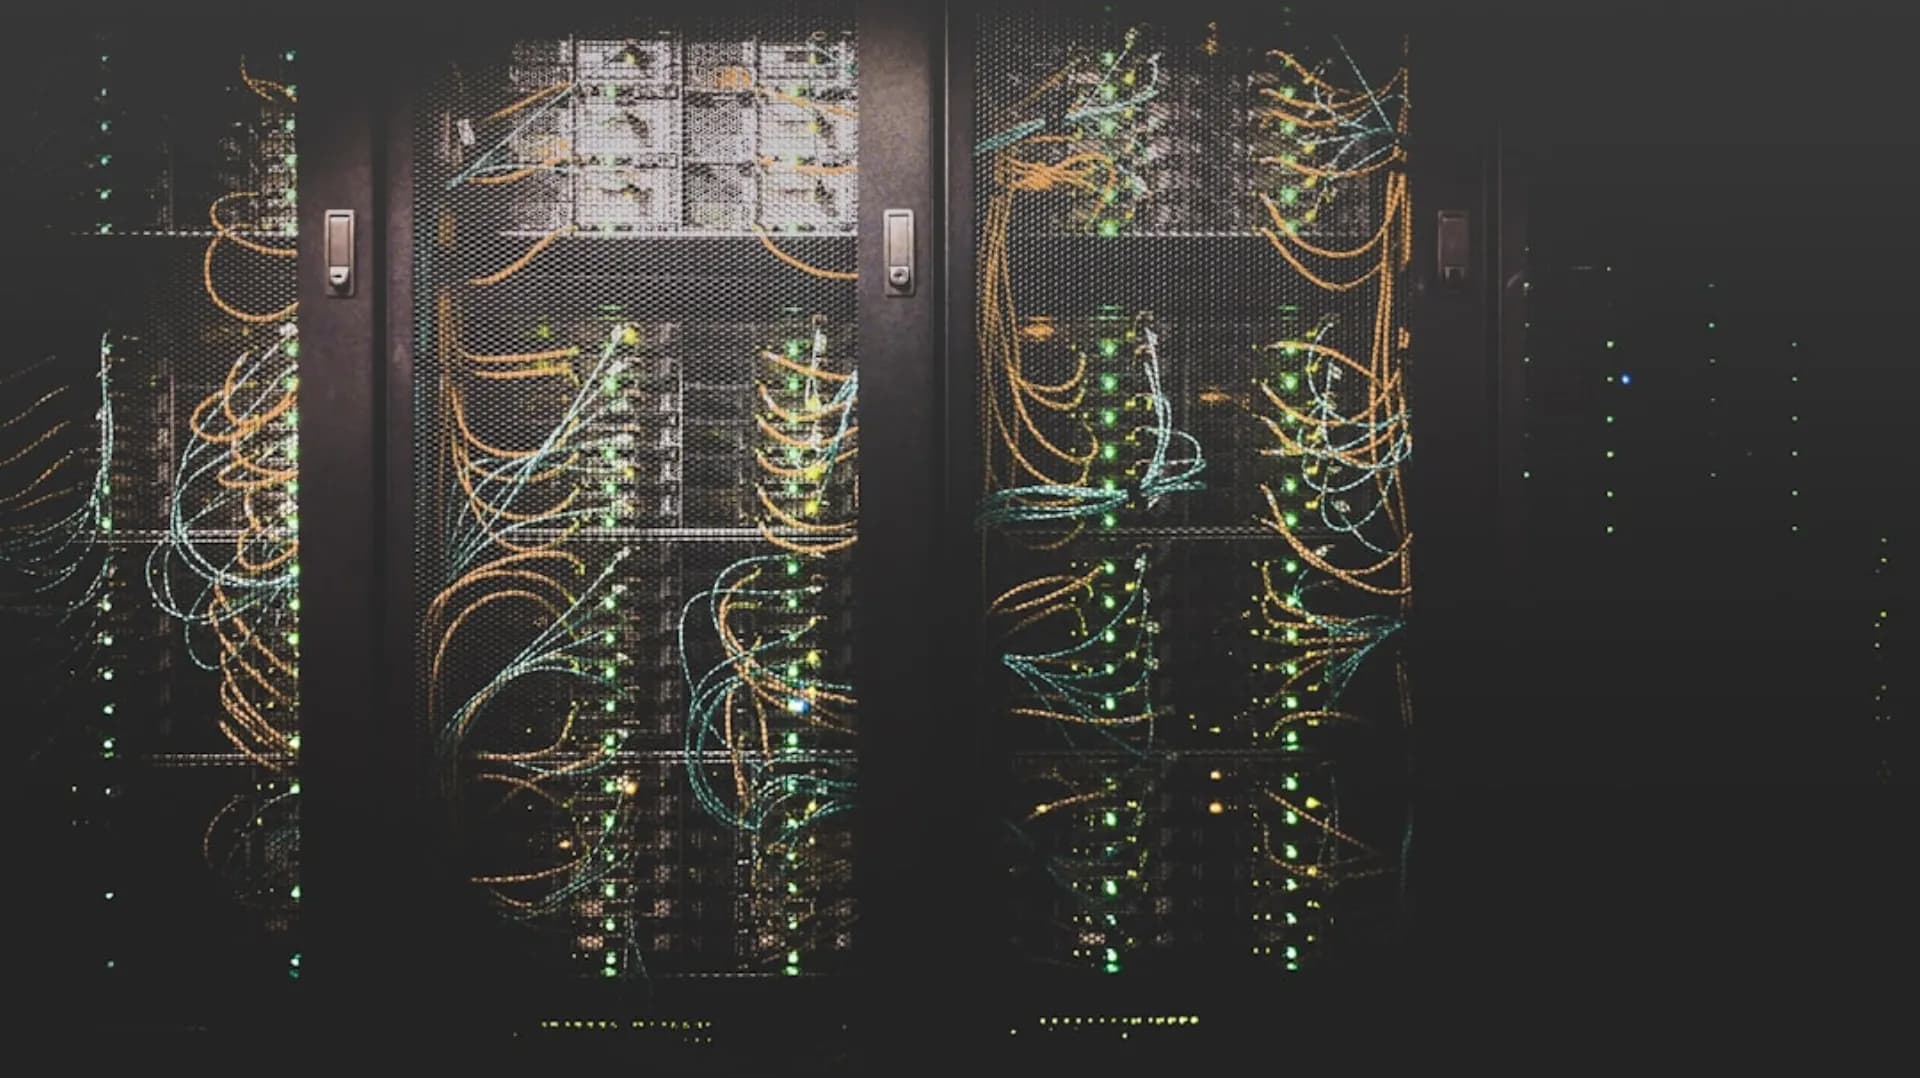
We deployed a self-hosted AI platform over 12 weeks — optimised for Korean financial services with native Korean language capability. (1) Korean-resident GPU infrastructure. Hardware: 32 NVIDIA H100 80GB GPUs across 4 server nodes, deployed in the financial group's primary data centre in Pangyo Techno Valley (the Seoul metropolitan area's technology hub, hosting many Korean financial and technology companies). Configuration: 8x H100 per node, 1.5TB system RAM, 24TB NVMe storage, InfiniBand HDR200 interconnect. The financial group's data centre met FSC/FSS requirements for critical data processing — Tier 3+ reliability, physical security, and access controls verified during annual FSS IT examination. Network: connected to the division's internal network, payment processing network, and fraud detection systems. No external internet connectivity for the AI cluster — all processing within the financial group's secure network boundary. (2) LLM-enhanced fraud detection: catching what statistics miss.
Architecture: two-tier fraud detection system combining existing statistical models (fast, processing every transaction) with LLM analysis (deep, processing flagged transactions). Tier 1 — statistical models (existing): gradient boosting models processing every transaction in 15ms — scoring transactions on 280 features (amount, location, time, merchant category, velocity, device fingerprint). Transactions scoring above threshold flagged for Tier 2 analysis. Threshold calibrated to capture 95 percent of actual fraud while flagging only 2.8 percent of all transactions for Tier 2 review. Tier 2 — LLM contextual analysis (new): Llama 3 70B fine-tuned on Korean fraud investigation data, processing flagged transactions with rich context. For each flagged transaction, the LLM analysed: transaction context (the sequence of recent transactions — was this purchase consistent with the cardholder's established pattern? Did the location sequence make geographic sense?
), communication context (recent customer service contacts — had the cardholder reported a lost card, asked about unfamiliar transactions, or exhibited behaviour consistent with social engineering?), merchant context (the merchant's transaction patterns — was this merchant showing anomalous transaction patterns suggesting collusion or terminal compromise?), and social network context (graph analysis of connections between cardholders, merchants, and devices — identifying fraud ring patterns). LLM processing time: 1.8 seconds per flagged transaction. Volume: 218,000 flagged transactions daily (2.8 percent of 7.8 million). The LLM providing a fraud probability score and natural-language explanation — enabling fraud analysts to understand why the AI flagged a transaction, not just that it was flagged.
Fine-tuning: 18,000 investigated fraud cases with Korean-language analyst annotations — the model learning Korean fraud investigation terminology, Korean social engineering patterns (specific to Korean culture — voice phishing scams targeting elderly Koreans, messenger phishing through KakaoTalk), and Korean merchant fraud typologies. (3) Korean-native customer service AI. Model: Mixtral 8x22B fine-tuned on 52,000 Korean-language customer interactions from the division's contact centre — learning: Korean financial terminology used by actual cardholders (colloquial terms, not formal financial language), appropriate Korean honorific levels (jondaenmal for standard interactions, more formal levels for complaint handling and elderly customers), Korean card-specific concepts (installment payment — halbu — options, point conversion processes, family card management, check card versus credit card differences), and resolution procedures (the division's specific processes for billing disputes, card replacement, limit changes, and fraud reporting).
Conversation quality: the AI handling multi-turn conversations in natural Korean — understanding context, following up on previous statements, and maintaining appropriate Korean conversation flow (different from English conversation patterns). Testing: 200 Korean-speaking evaluators (the division's contact centre quality team) blind-testing AI versus human responses — AI responses rated within 5 percent of human quality for standard inquiries. Integration: deployed as a first-contact AI, handling customer inquiries through the division's mobile app (primary channel — 68 percent of contacts), KakaoTalk channel, and web chat. Seamless escalation to human agents for complex issues, with the AI providing a conversation summary to the human agent (in Korean) for continuity. (4) Merchant intelligence platform.
Merchant risk scoring: LLM processing merchant data from multiple sources: transaction patterns (volume trends, average transaction size, refund rates, chargeback rates), financial health indicators (from business credit bureau data — Korean business credit reporting), public information (business registration changes, legal proceedings, industry news — processed from Korean-language sources), and network analysis (connections between merchants through shared terminals, common transaction patterns, and ownership structures). Risk model: producing merchant risk scores updated weekly, with high-risk merchants flagged for review by the division's merchant risk team. Early warning: the system identified 34 merchants that subsequently engaged in fraudulent activity (an average of 6 weeks before fraud was detected by traditional monitoring) and 28 merchants that went bankrupt (3 months average early warning — enabling the division to adjust credit limits and reduce exposure).
Merchant analytics: AI-powered insights for the division's merchant sales team — identifying: merchant acquisition targets (businesses in high-growth areas with card payment potential), competitive intelligence (merchants accepting competitor cards but not the division's cards — targeting for acquisition), and merchant retention risk (merchants showing declining transaction volume or increasing competitor card acceptance). (5) Korean language fine-tuning: financial Korean mastery. Training corpus: 52,000 customer interactions, 18,000 fraud investigation reports, 8,400 merchant risk assessments, 12,000 internal policy documents, and 4,200 regulatory correspondence documents — all in Korean. Korean financial vocabulary: the model learning 4,800+ Korean financial terms with contextual usage patterns. Korean morphological handling: fine-tuning specifically addressing Korean agglutinative morphology — ensuring the model correctly parsed Korean financial terms when combined with grammatical particles and suffixes. Korean evaluation: native Korean financial professionals evaluating model outputs across: language naturalness (4.6/5.0), financial accuracy (4.4/5.0), cultural appropriateness (4.7/5.0), and honorific correctness (4.8/5.0).